Identity Theft in Remote Onboarding: A Complete Guide
- Anti-Money Laundering (AML)
- Know Your Customer (KYC)
- Ongoing Monitoring
Fraudsters can exploit weaknesses in digital identity checks, stolen credentials and synthetic identities to bypass traditional fraud prevention controls.
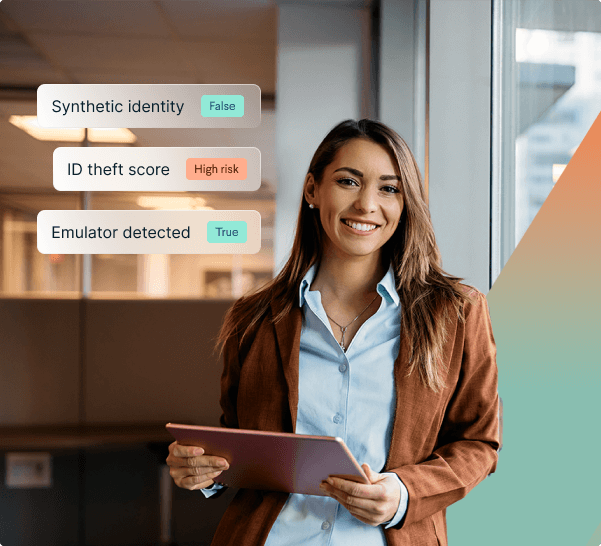
For financial institutions and fintechs, preventing identity theft requires more than a single verification check. Firms need connected controls that combine identity fraud detection, fraud prevention and ongoing monitoring.
Why Identity Theft Is a Risk in Remote Onboarding
Remote onboarding removes the need for customers to present themselves physically, making digital identity verification essential. However, fraudsters can exploit security vulnerabilities across the onboarding journey.
Stolen personal information, compromised credentials and manipulated documents can make fraudulent applications appear legitimate. In some cases, criminals may combine genuine information with fabricated details to create convincing identities.
This means relying on one fraud prevention service or identity check can leave gaps that criminals can exploit.
How Identity Theft Bypasses Fraud Prevention
Traditional fraud prevention often focuses on whether an individual’s identity documents appear genuine. While this remains important, it may not establish whether the person completing the application is genuinely entitled to use that identity.
Fraudsters can exploit:
- Stolen or compromised identity information
- Synthetic identities combining real and fabricated details
- Account credentials obtained through phishing or other attacks
- Gaps between identity verification and ongoing monitoring
- Inconsistent data across onboarding systems
These weaknesses can make identity theft difficult to detect without multiple layers of verification and risk assessment.
Strengthening Identity Fraud Detection
Effective identity fraud detection should assess more than documents alone. Regulated firms should consider combining identity verification with additional data sources, risk indicators and screening checks.
This can help onboarding teams identify inconsistencies earlier and determine when an application requires further investigation.
The objective is not simply to add more checks. It is to create a clearer picture of customer risk while keeping legitimate onboarding as efficient as possible.
The Role of Ongoing Monitoring
Identity theft does not necessarily end once an account has been opened. Criminals may take control of legitimate accounts or use compromised identities after onboarding.
Ongoing monitoring can help firms identify changes in customer behaviour and emerging risk that were not visible during the initial verification process.
Connecting onboarding checks with ongoing monitoring creates a more complete approach to fraud prevention and financial fraud risk.
Reducing Security Vulnerabilities
The strongest approach is to treat identity theft as an ongoing risk rather than a one-time onboarding problem.
Regulated firms should look for fraud prevention services that can:
- Verify identities using reliable data sources
- Identify inconsistencies and higher-risk applications
- Support AML and KYC processes
- Monitor customers beyond initial onboarding
- Integrate with existing compliance technology
- Reduce unnecessary manual reviews and friction
This helps compliance teams close gaps without creating unnecessary barriers for legitimate customers.
How SmartSearch Helps
SmartSearch brings identity verification, AML screening and ongoing monitoring together within a connected compliance workflow. This gives regulated firms greater visibility across the customer lifecycle while helping reduce reliance on fragmented checks.
For compliance and onboarding teams, the benefit is a more scalable approach to identity fraud detection, helping identify risk earlier while supporting a smoother customer experience.
Final Thoughts
Identity theft remains a significant challenge for remote onboarding because criminals can exploit gaps between identity verification, fraud prevention and ongoing monitoring.
The most effective approach is layered: combine robust identity checks with identity fraud detection, AML screening, risk assessment and continuous monitoring.
For regulated financial institutions and fintechs, choosing connected fraud prevention technology can help reduce security vulnerabilities, strengthen financial fraud controls and make remote onboarding more resilient.
See it in action
Get in touch with our team of experts today to discuss your business requirements and how SmartSearch can help with a bespoke solution.