Why 2026 is the year Source of Funds became a regulator's central control, and what firms need to do about it
- Anti-Money Laundering (AML)
- Monitoring & Reporting
- AML For Enterprise
- Source of Funds

For most of the last decade, Source of Funds has sat quietly within the broader anti-money laundering framework.
It has typically been viewed as a supporting control. A required check on higher-value transactions. A compliance process to complete before a matter could progress. For many firms, it was treated as an operational exercise rather than a core component of financial crime prevention.
That position is becoming increasingly difficult to maintain.
Throughout 2026, a series of regulatory, legislative and market developments have pushed Source of Funds much further up the compliance agenda. Across multiple regulated sectors, the ability to evidence where money has come from is no longer viewed as a niche requirement or a transaction-specific exercise. Instead, it is increasingly being treated as a critical control that helps firms understand risk, demonstrate regulatory compliance and protect themselves from financial crime exposure.
The direction of travel is unmistakable.
Source of Funds is becoming one of the most important controls within the wider compliance framework, and firms that continue to treat it as an administrative afterthought may find themselves increasingly out of step with both regulators and customers.
The Regulatory Landscape Is Changing
Several developments have contributed to this shift, but they all point towards the same conclusion: firms are being asked to build more evidence, maintain better records and demonstrate greater understanding of customer funds.
One of the clearest examples comes from the Solicitors Regulation Authority's updated Sectoral Risk Assessment, published in 2026.
Within the assessment, sources of funds and source of wealth were identified as key controls across multiple areas of elevated risk. Importantly, the SRA did not position these checks as isolated requirements associated with individual transactions. Instead, they were framed as controls that support a broader understanding of client risk and financial activity.
While the assessment is aimed at legal firms, the underlying principle extends much further.
Across multiple regulated sectors, supervisors are increasingly focused on evidencing the origin of money, understanding customer activity and demonstrating that risk assessments are based on appropriate information rather than assumptions.
The message is relatively simple.
Understanding where money has come from is no longer a supplementary compliance exercise.
It is becoming a foundation of effective due diligence.
The Failure to Prevent Fraud Offence Changes the Conversation
The Economic Crime and Corporate Transparency Act 2023 has already introduced significant changes across the economic crime landscape.
However, one of the most important developments for regulated firms is still ahead.
From 2027, the Failure to Prevent Fraud offence will come into force, introducing a new form of corporate criminal liability. Organisations will be expected to demonstrate that they had reasonable procedures in place to prevent fraud occurring within their businesses.
This changes the conversation around compliance.
Historically, firms could often focus on whether a fraud had occurred and who was responsible.
Increasingly, regulators and enforcement bodies will be interested in a different question: what steps did the organisation take to prevent it?
That distinction matters.
Evidence becomes critically important in a world where firms must demonstrate they acted reasonably.
Source of Funds processes play a significant role within that picture because they help create a documented record of how funds were assessed, what information was collected and what decisions were made.
For compliance leaders, this means Source of Funds should not be viewed simply as a procedural requirement.
It is increasingly becoming part of the evidence base that supports an organisation's wider financial crime framework.
Consumer Expectations Are Moving in the Same Direction
The regulatory case for stronger Source of Funds controls is increasingly clear.
What is perhaps more surprising is that customer expectations are evolving in much the same way.
For years, firms often worried that more robust compliance would create friction in customer journeys.
There is still some truth in that concern. Nobody enjoys being asked repeatedly for documentation or being forced to navigate complex administrative processes.
However, recent research suggests customers are increasingly willing to accept stronger compliance controls when they are implemented effectively.
Research conducted by Credas found that 80.9% of consumers consider regulation to be an important factor in determining whether they trust an organisation with their personal information. At the same time, almost seven in ten respondents stated they would stop working with a firm found to have breached compliance regulations.
These findings are particularly important because they reflect a broader change in public attitudes towards financial crime.
Customers are becoming more aware of fraud, scams and money laundering. They are also becoming more aware of the consequences when firms fail to manage those risks effectively.
As a result, compliance is increasingly influencing trust.
Firms that can demonstrate a clear, structured and professional approach to Source of Funds checks are not simply satisfying regulatory requirements. They are reinforcing customer confidence.
Compliance Frustration Remains a Problem
Of course, stronger compliance expectations create challenges as well.
The same Credas research found that 39% of homebuyers view proof of funds as the most frustrating part of the compliance process.
This creates a difficult balancing act.
Customers want firms to be compliant.
They expect appropriate controls.
They value trust and transparency.
But they also want those controls delivered efficiently.
Traditional Source of Funds processes often struggle to meet that expectation.
Manual document collection, lengthy email exchanges, repeated requests for information and fragmented evidence gathering can create frustration for both customers and compliance teams.
The challenge facing firms is therefore two-fold.
They need to strengthen their compliance position while simultaneously improving the overall customer experience.
Increasingly, those objectives must be achieved together.
Open Banking Has Changed What Is Possible
One reason this balancing act is becoming more achievable is the continued growth of Open Banking.
Consumer familiarity with sharing financial information through regulated digital channels has risen significantly in recent years. What was once viewed as a novel technology is now becoming a routine part of everyday financial interactions.
This matters because Open Banking changes the mechanics of Source of Funds verification.
Rather than relying solely on documents supplied by customers, firms can access structured banking information through regulated connections. This creates greater visibility, reduces manual handling and improves the quality of information available to compliance teams.
Importantly, it also helps create more consistent and defensible audit trails.
As regulatory expectations increase, the ability to evidence decisions clearly will become increasingly valuable.
For many firms, the conversation is no longer about whether Open Banking should play a role in Source of Funds processes.
The conversation is about how quickly those capabilities can be integrated into existing workflows.
Platform Data Suggests Firms Are Already Responding
The regulatory shift is already influencing behaviour.
SmartSearch platform data shows Source of Funds check volumes increasing significantly throughout 2026, reflecting growing demand for structured approaches to evidencing the origin of funds.
While property continues to account for a substantial proportion of activity, growth is increasingly visible across lending, wealth management, investment and broader financial services use cases.
This is an important point.
For many years, Source of Funds was associated almost exclusively with conveyancing and property transactions.
That perception is changing.
Firms across multiple sectors are recognising that the same underlying compliance challenge exists whenever significant funds are introduced into a regulated transaction.
Whether the transaction relates to property, lending, investments or professional services, the core question remains the same:
Can the organisation evidence the origin of funds in a way that is clear, consistent and defensible?
What Forward-Thinking Firms Are Doing
The firms adapting most successfully to this changing environment share several characteristics.
First, they are integrating Source of Funds into standard compliance workflows rather than treating it as an exceptional activity triggered only by specific scenarios.
Second, they are moving away from fragmented manual processes towards structured digital journeys that allow information to be collected consistently.
Third, they are treating Source of Funds as a customer experience issue as well as a compliance issue.
These firms recognise that compliance journeys influence customer trust. They understand that strong controls must be matched by efficient delivery.
Most importantly, they are viewing Source of Funds through a strategic lens rather than an operational one.
The objective is no longer simply obtaining evidence.
The objective is creating a repeatable process capable of demonstrating compliance, supporting risk decisions and improving transparency.
Where SmartSearch Fits
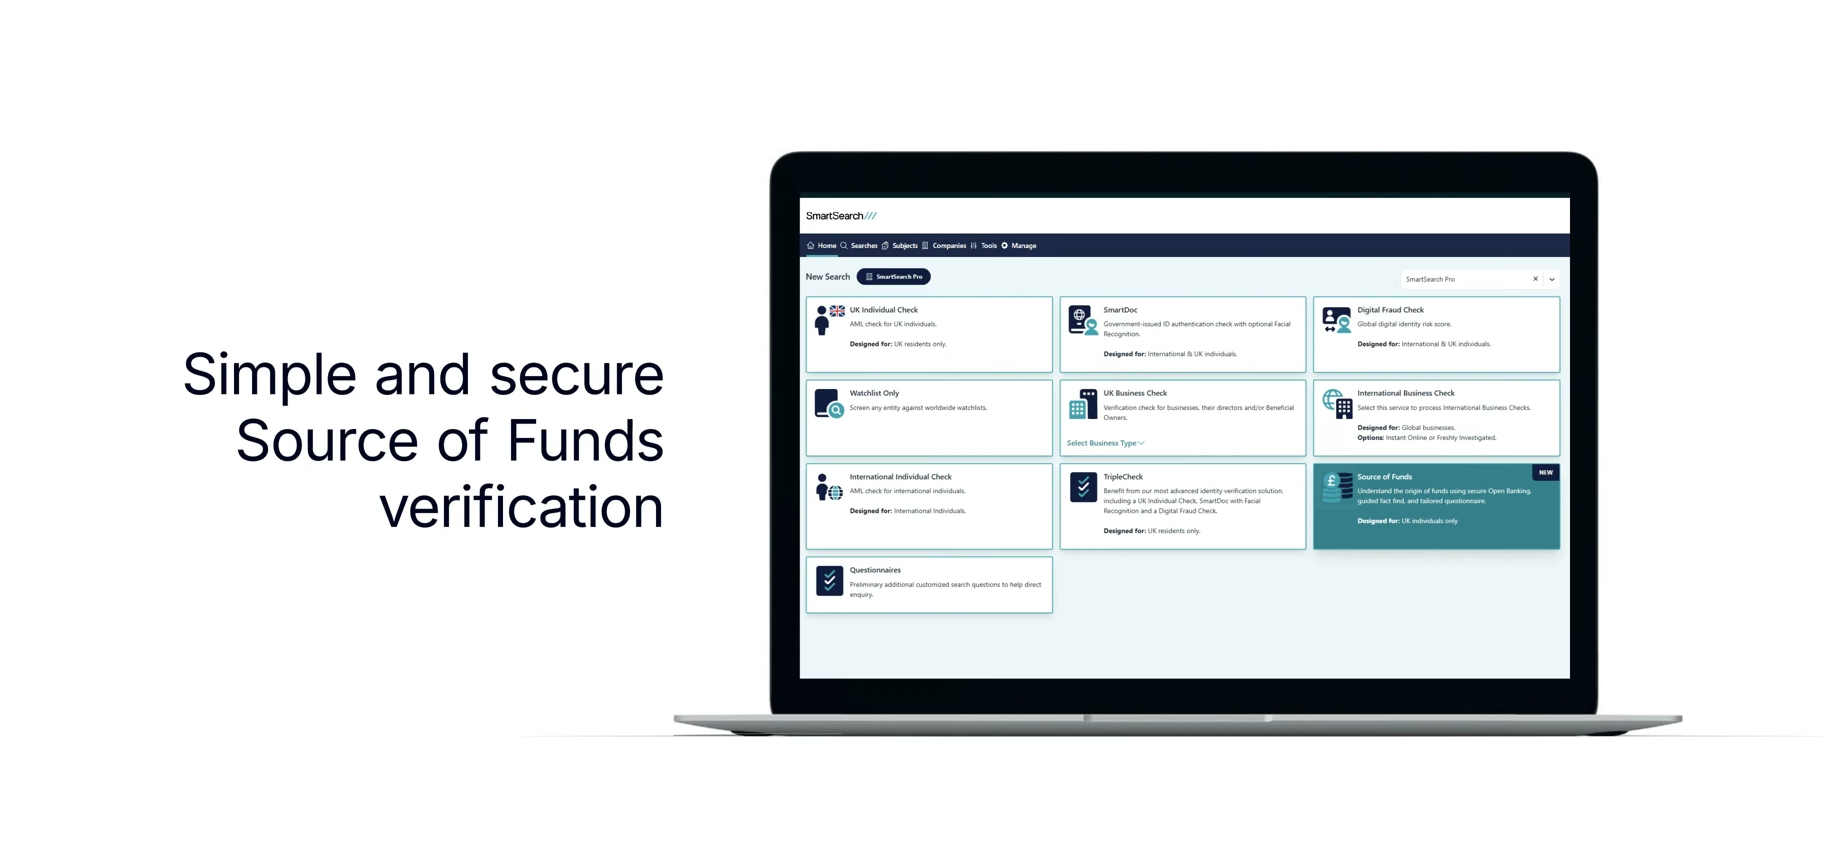
This is precisely the environment SmartSearch's expanded Source of Funds solution has been designed to support.
By combining structured customer journeys, Open Banking connectivity through FCA-authorised Armalytix and compliance-focused workflows, the platform helps firms build more consistent approaches to evidencing the origin of funds.
The goal is not simply to digitise an existing process.
It is to help firms adapt to a compliance environment where evidence, transparency and auditability are becoming increasingly important.
As regulatory expectations continue to evolve, firms need solutions capable of supporting both compliance obligations and customer expectations.
The Direction of Travel Is Clear
Source of Funds is no longer a niche control reserved for occasional high-value transactions.
It is becoming a central part of how regulated firms understand customer risk, demonstrate compliance and protect themselves against financial crime.
Regulators are demanding more evidence.
Legislation is increasing accountability.
Customers are placing greater value on trust and transparency.
And firms are recognising that traditional approaches may no longer be sufficient.
The organisations that respond proactively will be far better positioned to navigate the next stage of regulatory change.
The question is no longer whether Source of Funds matters.
The question is how effectively firms can incorporate it into the way they operate.
See it in action
Get in touch with our team of experts today to discuss your business requirements and how SmartSearch can help with a bespoke solution.